


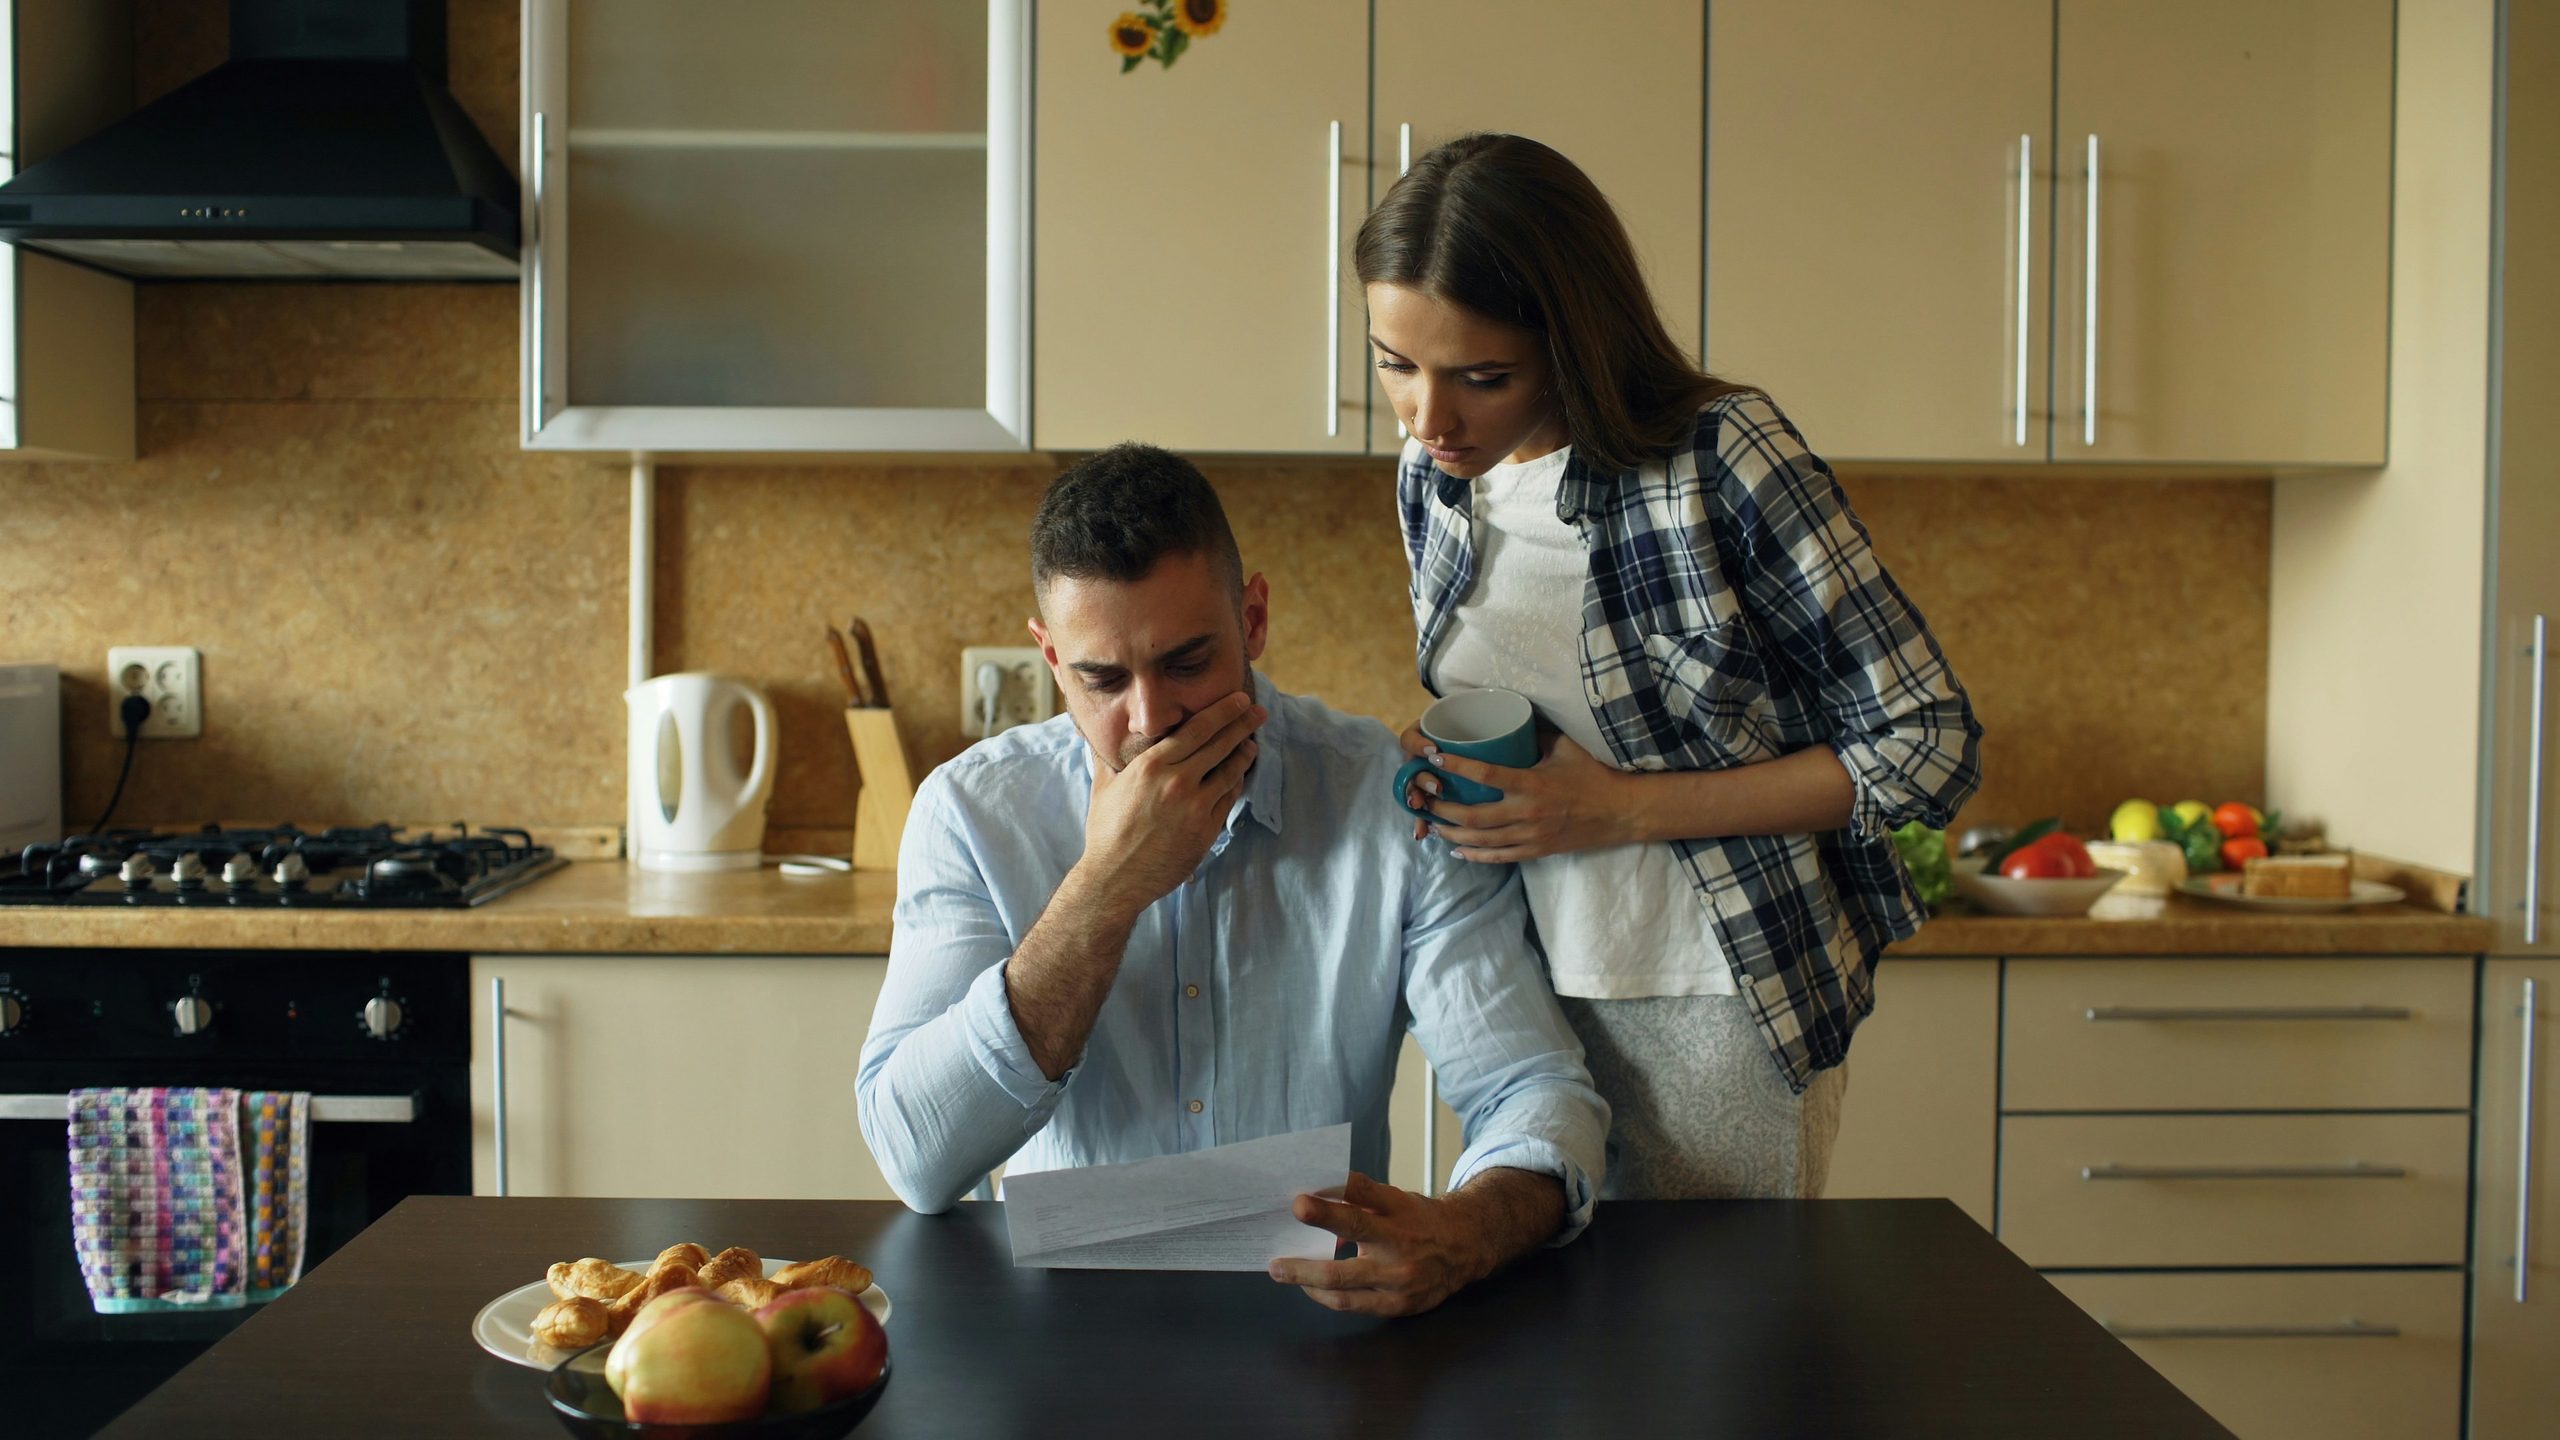
An unexpected bill can throw a family budget off course, especially when most of the month’s income is already allocated to household expenses. A broken appliance, an urgent car repair, or an unplanned medical expense can leave parents wondering how to cover the cost without falling behind on other responsibilities.
The pressure often comes from the timing rather than the expense alone. Money intended for groceries, utilities, or school activities might suddenly need to cover something more urgent. Instead of making a rushed decision, families can work through a few practical steps to understand the bill, find room in their budget, and manage the expense without creating further financial strain.
1. Check the Bill and Work Out What Is Actually Due
Before changing the household budget, examine the unexpected bill carefully. The amount listed might not tell the whole story, particularly when it involves medical treatment, vehicle repairs, or a service that includes several separate charges.
Start by checking the payment deadline, itemized costs, and any insurance coverage or service agreement that might apply. A medical bill could contain charges that need clarification, while a repair estimate might include maintenance that can safely wait. Asking questions before paying can prevent unnecessary spending.
Next, calculate how much money is actually missing. Suppose a family receives a $650 plumbing bill but has $200 available in a household repair fund. The immediate shortage is $450, provided the remaining expenses for the month are still covered. That distinction matters when deciding what to do next.
It is also worth confirming whether the entire amount must be paid immediately. Some bills have later deadlines than expected, while others involve deposits or separate payments. By establishing the correct amount and timing, families can respond to the actual problem rather than making decisions based on the initial shock.
2. Protect the Household Expenses That Cannot Wait
Once the amount is clear, review the money already committed to essential household expenses. Mortgage or rent payments, groceries, utilities, transportation, and childcare still need attention, even when an unexpected bill demands immediate payment.
The goal is to identify spending that can be postponed without disrupting everyday family life. Rather than making broad cuts, look at specific expenses that are flexible over the next few weeks. These might include:
- Restaurant meals and takeout,
- Entertainment purchases and outings,
- Nonessential subscriptions,
- Optional household decorations or upgrades.
Small adjustments can make a meaningful difference when combined. A family that postpones a $90 household purchase, reduces takeout spending by $60, and delays a $50 outing has freed up $200. That money can reduce the unexpected shortage without affecting essential bills.
However, the revised budget needs to remain realistic. Cutting grocery spending below what the family needs or using money reserved for transportation could create another problem before payday. Prioritize changes the household can manage comfortably, and avoid treating every available dollar as money that can safely go toward the unexpected expense.
3. Ask About Payment Extensions or Smaller Installments
An unexpected bill does not always need to be paid in one transaction. Before searching for additional money, contact the company or service provider and ask whether the payment deadline or amount due immediately can be adjusted.
Different providers offer different arrangements. A medical office might allow installment payments, a utility company could offer an extension, or a repair business might accept a deposit followed by another payment. These options are not guaranteed, but asking before the deadline can sometimes prevent unnecessary pressure.
For example, a $480 expense due this week might be difficult to cover alongside groceries and utility payments. If the provider agrees to two $240 installments, the family gains time to spread the cost across separate paychecks. The arrangement is useful only if both payments fit within the household’s available income.
Before agreeing, confirm the new payment dates, any additional fees, and what happens if an installment is late. Request written confirmation when possible. A manageable arrangement should provide genuine breathing room rather than simply moving an unaffordable payment to another date.
4. Consider How to Cover Any Remaining Shortage
After reviewing spending and exploring payment arrangements, a family might still face an essential bill that cannot wait. The remaining shortage could involve urgent medical treatment, a necessary home repair, or transportation needed to get to work.
At this stage, consider the resources already available. Emergency savings, assistance from community programs for which the family qualifies, or help from trusted family members might cover part of the expense. The most suitable option depends on the amount needed, how quickly payment is required, and the family’s ability to recover financially afterward.
When those resources are insufficient, someone who has previously struggled to qualify for credit might find themselves asking, “who will give me a loan when no one else will?” The question is understandable when a bill feels urgent, but borrowing options still need careful evaluation. Eligibility requirements, interest rates, fees, and repayment terms can differ significantly.
A loan is not automatically the best answer to an unexpected expense. Before accepting one, calculate the total repayment amount and consider how the payments will affect future household bills. If repayment would leave too little money for groceries, housing, or other necessities, borrowing could turn a temporary shortage into a recurring problem.
5. Adjust the Family Budget to Prepare for the Next Surprise
Once the immediate bill has been addressed, revisit the household budget. The expense might have reduced emergency savings, delayed a planned purchase, or introduced a new payment obligation. Each change affects how much money will be available over the coming weeks.
Start by updating the budget to reflect what was actually spent and what remains due. If $300 came from savings, decide how much can reasonably be returned each payday. If an installment arrangement was made, include those payments alongside regular bills rather than treating them as separate expenses.
Planning for irregular costs can also make future surprises easier to handle. School activities, vehicle maintenance, seasonal utility costs, and annual insurance payments are easier to manage when families put aside smaller amounts throughout the year. Using shared calendars and reminders to track upcoming payment dates can also prevent predictable expenses from being overlooked.
The aim is not to create a budget so restrictive that nobody can follow it. Even modest savings contributions and regular spending reviews can improve preparedness over time. A family that understands its usual expenses and keeps track of upcoming obligations is better positioned to respond when something unexpected happens again.
Keeping One Unexpected Bill From Becoming a Bigger Problem
An unexpected expense can disrupt even a carefully planned family budget. Checking the charges, protecting essential spending, and discussing payment arrangements can help families understand their options before committing money they might need elsewhere.
The most useful response is one that addresses the immediate bill without placing the next month’s responsibilities at risk. With realistic spending adjustments, careful decisions about borrowing, and gradual preparation for irregular expenses, families can handle financial surprises while keeping their everyday needs in view.

Leave a Reply